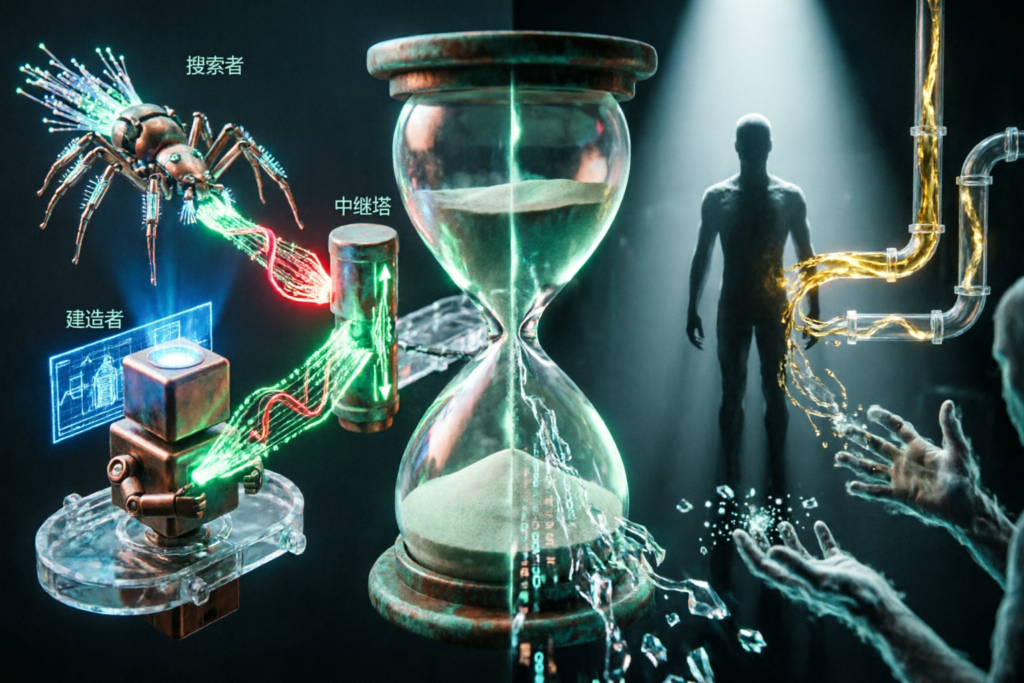
The MEV Supply Chain Revolution: How Block Builders, Searchers, and Relays Are Democratizing Extractable Value, Redefining Validator Economics, and Forcing Ethereum’s Most Controversial Fee Market Redesign Yet
On a typical morning in March 2023, a decentralized exchange trader on Ethereum tried to swap $50,000 of USDC for ETH. They set slippage tolerance at 0.5%, watched the transaction confirm, and ended up receiving roughly $300 less than the quoted price. Somewhere in the 12-second gap between broadcast and inclusion, an invisible supply chain had gone to work. A bot detected their trade, front-ran it with a larger position, pushed the price up, then back-ran the exit for profit. The trader never saw who did this. The validator who included the block likely didn’t know either. But several specialized intermediaries coordinated the extraction, split the proceeds, and moved on to the next opportunity before the trader’s wallet even updated.
This is Maximal Extractable Value in action, and until recently, it operated like a black market. Searchers wrote bots, validators ran them directly or took opaque side payments, and users bore the costs without recourse. The post-Merge Ethereum landscape has transformed this into something more structured and, paradoxically, more contentious. A formal supply chain now exists: independent searchers hunt for opportunities, block builders assemble transactions into profitable bundles, relays validate and transmit these blocks, and validators simply sign off. Each party takes a cut. The system looks more efficient on paper. Whether it serves anyone beyond the supply chain itself remains the central question of Ethereum’s most divisive fee market debate since EIP-1559.
What makes this moment particularly urgent is the scale. MEV extraction has generated an estimated $1.2 to $1.5 billion in cumulative revenue since 2020, with roughly $100 to $200 million annually flowing through the builder-relay infrastructure that emerged after Ethereum’s shift to proof-of-stake. The concentration is stark: a handful of builders produce the majority of blocks, two or three relays dominate traffic, and the entire edifice rests on trust assumptions that technical purists find unacceptable. Ethereum’s core developers are now weighing proposals that could reshape block production entirely, from inclusion lists to proposer commitments to enshrined builder roles. The next 18 months may determine whether Ethereum remains credibly neutral or drifts toward managed extraction.
What MEV Actually Is, and Why It Escaped the Basement
MEV began as “miner extractable value” on proof-of-work Ethereum, referring to any profit a block producer could extract by reordering, inserting, or censoring transactions. The canonical example is arbitrage: if a large trade moves a token price on Uniswap relative to Binance, whoever gets their arbitrage transaction into the next block captures the difference. Miners could run these strategies themselves, sell block space to searchers, or simply ignore the opportunity.
The Merge changed the actor but amplified the problem. Validators with 32 ETH stakes are not typically sophisticated trading operations. They lack the infrastructure to build optimal blocks, and their rewards from vanilla block production dropped substantially after the shift to proof-of-stake. This created a vacuum. Specialized block builders, many spun out of existing MEV search operations, stepped in to offer validators pre-built blocks that included far more value than they could assemble themselves. The validator’s job simplified to choosing the highest bid, signing the block header, and collecting payment.
The supply chain crystallized into roughly this flow: searchers monitor the mempool and private order flows, construct bundles of transactions that exploit or protect against MEV opportunities, and submit these to builders. Builders aggregate bundles and ordinary transactions, simulate outcomes, and assemble complete blocks. Relays receive these blocks, verify their validity and payment promises, and hold them in escrow. Validators connect to relays, receive block headers with payment commitments, sign blindly, and only then receive the full block body. This “blind signing” prevents validators from stealing MEV strategies, but introduces its own trust requirements.
The Anatomy of the Modern MEV Supply Chain
Searchers: The Opportunity Hunters
Searchers operate at the bleeding edge of Ethereum’s execution layer. They run modified nodes with custom mempool monitoring, maintain direct connections to major DeFi protocols, and invest heavily in latency reduction. Some run statistical arbitrage across decentralized exchanges. Others specialize in liquidation bots for lending protocols like Aave and Compound. A growing segment focuses on “intent-based” strategies, solving user-specified outcomes through complex routing rather than simple transaction submission.
The searcher landscape has stratified. Top-tier operations reportedly spend $10,000 to $50,000 monthly on infrastructure alone, co-locating servers with major validators and maintaining redundant systems across multiple cloud providers. Entry-level searchers increasingly struggle. Flashbots, the research organization that pioneered much of this infrastructure, estimated in 2022 that median searcher profit margins had compressed to single-digit percentages for common strategies, with only novel approaches or substantial capital deployment remaining viable.
Block Builders: The New Power Brokers
Block builders represent the most consequential concentration of power in post-Merge Ethereum. As of early 2024, data from mevboost.org and similar trackers consistently showed that two to four builders produced 60 to 80 percent of MEV-Boost blocks. Beaverbuild, Flashbots, and a rotating cast of smaller competitors compete on payment to validators, but the barriers to entry are substantial. Effective building requires massive simulation infrastructure, relationships with searchers for exclusive flow, and sophisticated pricing algorithms.
The builder business model is straightforward in theory, tricky in practice. They bid to validators based on expected block value, hoping their simulation outperforms rivals. They profit when block value exceeds their bid, lose when they overestimate, and face constant pressure to offer searchers favorable terms to maintain flow. Some builders integrate vertically, running search operations themselves. Others position as neutral aggregators, though neutrality claims are difficult to verify.
Relays: The Trust Bottleneck
Relays sit uncomfortably in this supply chain. They are technically simple, politically loaded. A relay’s core function is receiving blocks from builders, validating them against consensus rules, and presenting headers to validators with payment guarantees. But they can censor, delay, or simply fail. The OFAC compliance debates that erupted after Tornado Cash sanctions in 2022 centered largely on relay behavior, with some relays filtering transactions involving sanctioned addresses and others maintaining neutrality.
The relay market has consolidated even more sharply than building. For extended periods, a single relay (Flashbots’) carried the majority of MEV-Boost traffic. This creates a systemic vulnerability: relay downtime or censorship decisions affect block production across all connected validators. Proposals for distributed or enshrined relay functions aim to address this, but implementation remains contentious.
Real-World Mechanics: How the Money Flows
Consider a concrete liquidation on Aave in late 2023. A borrower with $2 million in ETH collateral had their position approach the liquidation threshold as prices dropped. Multiple searchers detected this. One, with superior mempool positioning and perhaps a private transaction from the borrower themselves, constructed a bundle: their own transaction to liquidate the position, a back-run to swap the seized collateral efficiently, and perhaps a payment to the builder for priority inclusion.
The builder receiving this bundle simulated it against competing opportunities. Perhaps a large DEX arbitrage offered higher gross value but carried execution risk. The liquidation bundle was cleaner, more certain. The builder incorporated it, added other profitable transactions, and computed a validator payment of 0.05 ETH above the next-best builder’s expected bid.
The relay received this block, verified it paid more than the local block the validator could build, and presented the header. The validator, running MEV-Boost or equivalent software, compared bids from multiple relays, selected the highest, and signed blindly. Twelve seconds later, the block propagated, the liquidation executed, and the supply chain participants split roughly $15,000 in extracted value. The original borrower lost their collateral premium. The Aave protocol functioned as designed. The system, viewed narrowly, worked.
This pattern repeats thousands of times daily. Data from EigenPhi and other MEV analytics platforms suggests that arbitrage dominates volume but liquidations and sandwich attacks generate higher per-transaction profits. The distribution is highly skewed: a 2023 analysis found that roughly 10% of searchers captured 70% of identifiable MEV profits, with the long tail operating at or near loss.
The Democratization Mirage
Proponents frame the builder-relay structure as democratizing MEV access. Previously, only large mining pools could reliably extract value. Now, theoretically, any validator can access sophisticated block building through MEV-Boost. Small searchers can submit to multiple builders rather than negotiating directly with miners. Users can access “MEV protection” through private mempools or order flow auctions.
The reality is more qualified. Access to top builder payment streams is not equal. Searchers with exclusive relationships or proprietary flow get better terms. Validators running default configurations connect to dominant relays, reinforcing concentration. Users of MEV protection services often pay implicitly through worse execution or explicitly through fees, with limited transparency into whether protection actually improves their outcomes.
The most credible democratization has occurred at the validator level. Solo stakers and small pools can indeed compete with large operations on MEV revenue, since builder markets are competitive at the margin. This was a genuine improvement over proof-of-work, where mining pool operators captured most extractable value directly. But the concentration upstream, in building and relaying, introduces new forms of centralization that may prove harder to dislodge.
Risks, Limitations, and Trade-Offs
Technical Vulnerabilities
The current architecture contains several failure modes that could disrupt Ethereum’s liveness or fairness. Relay censorship, whether voluntary or legally compelled, can delay transaction inclusion. Builder market concentration creates single points of failure; a dominant builder going offline could force validators to revert to local block building with substantially reduced rewards. The blind signing mechanism, while protecting searchers, prevents validators from verifying block contents, creating potential for malicious payload delivery that consensus clients must catch.
More subtly, the simulation race between builders consumes enormous computational resources for socialized benefit. Multiple builders independently simulating identical transaction sets represents deadweight loss from a network perspective, though individually rational competition.
Regulatory and Legal Exposure
The MEV supply chain sits in uncomfortable regulatory territory. Searcher activities often resemble market manipulation in traditional finance, though decentralized execution complicates jurisdictional claims. Builder and relay operations face potential money transmission or securities law exposure, particularly if they begin selecting transactions based on content rather than neutral criteria. The Tornado Cash sanctions demonstrated that relay operators can be pressured to censor, and legal frameworks for non-custodial intermediaries remain undeveloped.
Validators themselves occupy ambiguous ground. Those running MEV-Boost delegate block construction but remain the legally accountable block proposers. Whether this constitutes sufficient decentralization to avoid liability, or merely obscures responsibility, is untested in courts.
Economic and User Harms
The fundamental critique of MEV extraction remains: it represents value transfer from ordinary users to sophisticated intermediaries, with questionable social benefit. Arbitrage improves price efficiency, but the same efficiency could theoretically be achieved with less extraction. Liquidations are necessary for protocol solvency, but MEV competition often means borrowers pay more in liquidation penalties than minimum required. Sandwich attacks are nearly pure harm to the targeted trader.
Order flow auctions and other “fair ordering” mechanisms may reduce some harms but introduce their own: complexity, potential for auction manipulation, and the fundamental question of who deserves to capture value from transaction ordering.
The Credible Neutrality Crisis
Perhaps the deepest risk is to Ethereum’s social contract. The network’s value proposition rests partly on credible neutrality, the assurance that no privileged party controls transaction inclusion. The builder-relay structure, while formally permissionless, concentrates practical influence in ways that resemble the financial intermediaries Ethereum sought to displace. If users perceive that block production is managed by a cartel of specialized operators, the ideological foundation weakens even if technical decentralization metrics appear acceptable.
Practical Guidance for Navigating the MEV Landscape
For Traders and DeFi Users
-
Understand your slippage settings. The 0.5% default on many DEX interfaces is often excessive for liquid pairs and insufficient for thin markets. Use tools like CowSwap, 1inch’s Fusion mode, or other intent-based routing that aggregates liquidity and provides MEV protection.
-
Consider private transaction submission. Services like Flashbots Protect or mempool privacy features from wallets like Rainbow can prevent frontrunning for non-time-sensitive transactions. Be aware that private submission may increase inclusion delay.
-
Monitor your transaction outcomes. Tools like EigenPhi, MEV-Explore, or wallet-specific features can reveal whether you’ve been sandwiched or otherwise extracted against. Pattern recognition helps you adjust behavior.
-
For large trades, break execution across blocks or use dedicated protocols. Protocols like UniswapX, CoW Protocol, or institutional OTC desks can access off-chain liquidity and sophisticated execution that reduces MEV exposure.
For Validators and Node Operators
-
Diversify relay connections. Running MEV-Boost with multiple relays, including non-censoring options, improves resilience and supports network health. Tools like the MEV-Boost relay dashboard help monitor relay performance and censorship rates.
-
Evaluate builder payment consistency, not just headline bids. Some builders occasionally overbid and fail to pay; track actual realized payments over time.
-
Consider local block building as fallback. Ensure your node can build locally if relay infrastructure fails, even if this means lower rewards temporarily.
-
For large operations, evaluate running your own builder. The fixed costs are substantial but may be justified at scale, and contributes to builder diversity.
For Protocol Developers and Entrepreneurs
-
Design with MEV in mind from inception. Mechanisms that create discrete, predictable value moments (liquidations, oracle updates, auctions) will be exploited. Consider continuous mechanisms, randomized ordering, or encrypted mempools where technically feasible.
-
Explore application-layer MEV capture. Protocols like MakerDAO, Lido, and others have begun capturing some MEV directly rather than leaving it to external searchers. This requires careful governance design but can align incentives.
-
Contribute to censorship resistance. Whether through distributed relay networks, encrypted transaction propagation, or other mechanisms, the ecosystem needs alternatives to concentrated infrastructure.
For Investors and Analysts
-
Evaluate MEV exposure in protocol tokenomics. Protocols that ignore MEV often leak value; those that capture it may create sustainable revenue. Assess whether capture mechanisms are durable or subject to competitive erosion.
-
Monitor builder and relay concentration metrics. Sudden shifts in market share can indicate technical problems, regulatory pressure, or emerging centralization risks.
-
Distinguish MEV infrastructure plays from MEV extraction strategies. The former (relays, block builders, software tools) may offer more sustainable returns than direct searching, where margins compress rapidly.
The Road Ahead: Enshrinement, Fragmentation, or Something Else
Ethereum’s core developers face genuinely difficult choices. The current MEV-Boost ecosystem is an external software layer, not a protocol-native mechanism. This has allowed rapid innovation but creates trust assumptions and centralization pressures that many find unacceptable.
Several paths are being actively explored, though none is certain to prevail. “Enshrined proposer-builder separation” would protocolize the builder role, potentially with cryptographic guarantees that prevent builder censorship or validator stealing. “Inclusion lists” would require validators to include certain transactions, limiting builder discretion. “Encrypted mempools” using threshold encryption or other techniques would prevent searchers from seeing pending transactions until ordering is fixed.
Each approach carries trade-offs. Enshrinement risks ossifying a design that may prove suboptimal. Inclusion lists may be circumvented or may reduce builder economic viability. Encrypted mempools introduce latency and complexity that could harm user experience. The timeline for any of these remains uncertain; core developer discussions suggest that substantial changes are unlikely before 2025, with incremental adjustments more probable in the near term.
What seems clearer is that the MEV supply chain will not remain static. Regulatory pressure on relays and builders is likely to increase. Layer-2 rollups are developing their own MEV dynamics, sometimes replicating and sometimes diverging from mainnet patterns. Cross-chain MEV, already significant between Ethereum and its rollups, will grow as interoperability improves.
For participants in this ecosystem, the practical imperative is engagement rather than passive acceptance. The current structure emerged from specific technical and economic conditions; it can be reshaped by collective action, protocol design, and market innovation. The question is whether that reshaping serves broad user interests or merely redistributes extraction among slightly different intermediaries.
The trader who lost $300 to an unseen supply chain deserves a system where such extraction is either impossible or transparently compensated. We are not there yet. The builder-relay infrastructure is a step toward visibility, but visibility without accountability is just better-documented extraction. The next phase of Ethereum’s evolution will be measured by whether it can close that gap.
What to Do Next
- Compare 2-3 relevant tools before choosing one.
- Validate fees, custody model, and jurisdiction support.
- Start small and track performance weekly.
Recommended Next Reads
- Crypto security basics:
/category/cybersecurity/ - DeFi risk management:
/category/defi/ - Blockchain technology explainers:
/category/blockchain-technology/
Sources and Further Reading
FAQ
What is the main takeaway?
Focus on practical risk, utility, and execution rather than hype.
Who should care most?
Builders, active users, and investors exposed to the discussed sector.
What should readers do next?
Use the checklist, compare tools, and validate claims with primary sources.
Stay Updated
Subscribe to your site newsletter for weekly market breakdowns, tool comparisons, and risk alerts.